How to Choose a Health Insurance Plan
A simple framework for comparing plans without choosing only by the monthly premium.
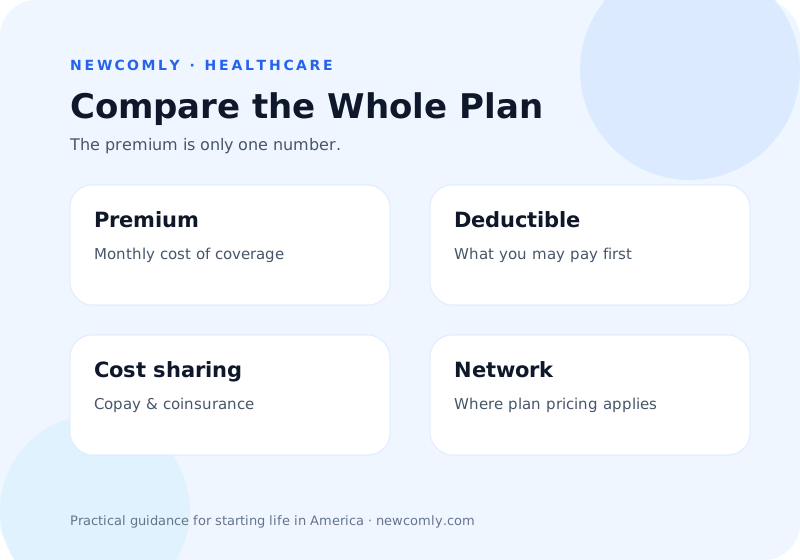
Compare four things together: monthly premium, expected out-of-pocket costs, the provider network, and the services or prescriptions you expect to use. Marketplace metal levels describe how costs are split—not the quality of medical care.
1. Start with total cost, not premium alone
A premium is the monthly price of keeping coverage. Your actual yearly cost can also include a deductible, copayments, and coinsurance. A lower-premium plan can cost more overall if you use substantial medical care.
2. Understand Marketplace metal levels
Marketplace plans are grouped into Bronze, Silver, Gold, and Platinum categories. HealthCare.gov explains that the categories reflect how costs are generally shared between you and the plan; they are not ratings of care quality.
| Compare | Question to ask |
|---|---|
| Premium | Can I comfortably pay this every month? |
| Deductible | How much might I pay before many benefits begin sharing costs? |
| Copay / coinsurance | What will common visits, tests, prescriptions, or hospital care cost me? |
| Out-of-pocket maximum | What is my upper limit for covered in-network cost sharing for the year? |
| Network | Are my doctors, hospital, pharmacy, and specialists in-network? |
3. Check the network before enrolling
HMO, PPO, EPO, and POS plans can handle out-of-network care differently. HealthCare.gov notes that some plans generally cover only in-network care except emergencies, while others may allow out-of-network care at a higher cost.
4. If you qualify for extra savings, pay attention to Silver
HealthCare.gov says cost-sharing reductions are available only through Silver Marketplace plans for people who qualify. That can materially change deductibles and other out-of-pocket costs.
A newcomer comparison method
- Write down current doctors, medications, and recurring care.
- Check each plan’s provider directory and drug formulary.
- Compare premium plus realistic expected usage.
- Look at the out-of-pocket maximum for a difficult year.
- Read the Summary of Benefits and Coverage before enrolling.
Official sources
- HealthCare.gov — Plan CategoriesExternal site ↗
- HealthCare.gov — Plan & Network TypesExternal site ↗
- HealthCare.gov — DeductibleExternal site ↗
This article provides general educational information, not individualized medical, legal, tax, immigration, or insurance advice. Coverage rules and plan terms can change. Verify current requirements with the relevant government agency, insurer, employer, or qualified professional.